key insights:
- The core dispute is not only future dilution. Shareholders are challenging the 273 million additional potential shares already created.
- The lock-up limits immediate selling pressure but does not reverse dilution. Gerovich’s 64.032 million new shares remain part of the company’s issued equity.
- The MMXX issue remains unresolved. Gerovich denied directing its trades, but the supplied record does not fully establish its beneficial ownership structure.
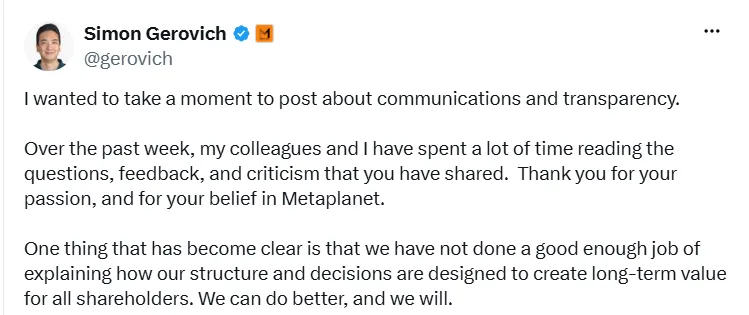
Metaplanet shares fell about 7% on Monday after CEO Simon Gerovich addressed shareholder criticism over executive compensation and his connection to major shareholder MMXX Ventures. The Tokyo-listed Bitcoin treasury company now faces questions about dilution, governance oversight and whether its August reforms went far enough.
The option plan expanded with Metaplanet’s share count
Metaplanet established its Series 10 Stock Acquisition Rights program in December 2022, well before it adopted its Bitcoin treasury strategy. Shareholders approved the plan in February 2023, with 460,000 rights issued to seven officers and employees.
Everybody had 100 shares for 2 rights and the structure was based on approximately 20% of fully diluted share capital. But this mechanism took off when Metaplanet switched to Bitcoin transactions in April 2024.
The company started issuing shares and warrants to fund its Bitcoin acquisition efforts more and more. Therefore, the number of shares increased and the pool of Series 10 increased as well. The amount of potential rewards allocated had reached 319.464 million shares by August 2026. Metaplanet then removed the automatic adjustment mechanism on August 18 and fixed the pool at that level.
The company also introduced a five-year transfer restriction. However, it did not return the pool to its size when the Bitcoin strategy began. That decision remains the central shareholder complaint.
Gerovich exercises rights as scrutiny intensifies
Ten days after the amendment, Gerovich exercised 92,000 Series 10 rights. The exercise resulted in the creation of 64.032 million new shares and made his current holding of the shares to 79.5875 million.
Metaplanet held onto those newly-minted shares under the five-year restriction. In its updated terms, the restriction will last until August 17, 2031.
Gerovich previously held 276,000 of the remaining Series 10 rights disclosed at the end of June. Other executives and employees also held rights under the program. The exercise therefore represented only part of Gerovich’s disclosed position.
Shareholder criticism has focused on the 273 million shares added through the adjustment mechanism after the Bitcoin strategy began. That figure comes from outside analysis and does not represent an official Metaplanet calculation.
MMXX relationship adds another governance question
On September 6, Gerovich directly addressed the MMXX controversy. He said he was a major shareholder in MMXX’s holding company, but not a majority shareholder. He also denied having played any role in MMXX’s investment and trading decisions. Gerovich said that he needed to better understand the relationship and compensation model.
The provided figures show that MXX owns approximately 42.47 million Metaplanet shares. This is about 3.26% of the company. Public filings create ties between Gerovich and MMXX. However, they do not completely determine the identity of all beneficial owners of MMXX’s parent.
Analysis of shareholders’ deals has also claimed that MMXX traded off about 50 million Metaplanet shares in the year of the 2024 rally. Metaplanet has not been able to independently substantiate that amount in its dispute.
Similarly, the documents that are made available do not create any record of the extent of economic gain that Gerovich personally enjoyed from any MMXX transactions. The significance of this is that there is a difference between voting influence and legal ownership/economic interest.
Gerovich admitted that the deal wasn’t satisfactorily explained to Metaplanet. But his remarks did not involve him in the cancellation of the additional rights or reveal the full ownership of MMXX.
Bitcoin strategy raises the stakes
Metaplanet’s dispute reflects a broader challenge for companies adopting Bitcoin treasury strategies. These firms often rely on equity financing to increase their Bitcoin holdings.
That approach can expand corporate Bitcoin exposure while reducing existing shareholders’ percentage ownership. Executive compensation tied to the same expanding share base can magnify those concerns.
Metaplanet has expanded its Bitcoin holdings to 43,000 BTC while its stock has fallen sharply from its 2025 peak. The company’s shares dropped about 43% this year by September 7, according to the supplied market data.
Meanwhile, the Nikkei 225 gained about 31% over the same period.
The performance gap adds pressure because investors increasingly assess Bitcoin treasury companies on per-share value rather than Bitcoin holdings alone.
Metaplanet also plans to commit 2,100 BTC and $2.5 million to a proposed US Bitcoin treasury platform involving Nasdaq-listed Super League. If completed, the transaction would broaden the company’s strategy beyond its existing treasury operations.
Investors await further disclosures
Metaplanet has not announced an independent review, special investigation or shareholder vote over the Series 10 plan. The next scheduled vesting date falls on February 8, 2027.
Investors will likely watch for details about the proposed long-term incentive vehicle and the rights expected to move into it. They will also want to know more about the performance conditions and ownership arrangements.
Metaplanet has not yet resolved some of the historical issues, but has answered the questions for the future. In addition to that, the company has halted any additional automatic allocation expansion, but the increased allocation will still be there.
This leaves shareholders faced with two contrasting realities. Metaplanet keeps amassing its Bitcoin treasury, and its financing and compensation models are increasingly being called into question for transparency.