key insights:
- CFTC registration of controlled trading protocols for DeFi: The bill would establish.
- Politics: Republicans still require Democratic votes to make 60 votes.
- Regulation: Despite broader negotiations, regulation of both rewards for conducting business and rewards for stablecoins are still a work in progress.
Senate Republicans make CLARITY Act changes ahead of September 15 procedural vote, introducing new DeFi registration rules. The draft, which is 630 pages long, also clarifies credit union crypto activity, albeit ethics debates remain a risk to Democratic support.
The new bill was passed around by Republican lawmakers on Sept. 10 following weeks of talks during the August recess. The changes will respond to a number of Democratic requests, but will largely leave intact the most politically sensitive provisions.
Revised DeFi rules draw a sharper line
The revised CLARITY Act creates a category for non-decentralized finance trading protocols. The provision addresses platforms that have identifiable control over functions, operations, and/or consensus rules.
Under the proposal, covered protocols would need to register with the Commodity Futures Trading Commission. The CFTC and Treasury Department would then write rules to be applied to various structures of governance.
The language’s attempt to differentiate projects under the control of certain identifiable individuals or groups from truly decentralized networks. But there are already questions about the definition among DeFi players.
Crypto developer Roman Storm raised a question about how a project which bills itself as “DeFi” can also be “non-decentralized.” There has been debate regarding the regulatory responsibility in terms of governance, upgrades and operational control.
The revised language also limits the DeFi provisions to spot and cash digital commodity transactions. Senator Cynthia Lummis said the change addresses concerns raised by Native American tribes about potential effects on prediction markets.
Credit unions also received clearer authority to conduct digital asset activities under the updated legislation.
Democrats still hold the crucial votes
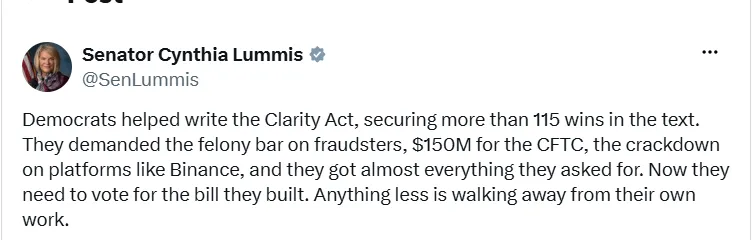
Lummis said Republicans included than 114 provisions that Democratic senators asked for. She said these changes show the legislation is a bipartisan compromise, not just something pushed by Republicans alone.
She pointed to changes like a felony bar aimed at fraudsters and $150 million in funding for the CFTC. She also mentioned rules targeting crypto platforms such as Binance. But, as yet, the Democrats have not come out with any official endorsement of the new text. Republicans hold 53 Senate seats and the bill relies on votes to make it to the magic 60.
The vote on the motion to proceed is on Sept. 15. That means it’s not a decision, on the bill. Instead it would allow debate and possible amendments to happen. White House crypto adviser Patrick Witt urged senators from both parties to advance the bill. Treasury Secretary Scott Bessent also called for lawmakers to keep negotiations alive.
Ethics dispute remains the main obstacle
The revised CLARITY Act leaves its ethics provisions largely intact. Those provisions restrict public officials, government employees, and their spouses from issuing or sponsoring digital assets. The Justice Department would hold primary enforcement authority under the proposal. The restrictions would also expire in January 2029.
Democrats have demanded broader restrictions on crypto interests held by senior government officials. Their concerns intensified after scrutiny of President Donald Trump’s financial connections to crypto businesses.
A separate proposal supported by Democratic senators and Republican Senator Thom Tillis sought stronger restrictions. The September 10 draft did not adopt major elements of that alternative.
Coinbase CEO Brian Armstrong previously said lawmakers had resolved issues his company considered essential. He also identified ethics negotiations as one of the remaining matters requiring agreement.
Stablecoin rewards present another unresolved dispute. Banking groups want tighter restrictions, while crypto advocates argue that transaction incentives differ from interest paid on deposits.
Senate vote could determine crypto framework
The immediate significance of the CLARITY Act centers on the September 15 procedural vote. If it fails to get 60 votes, the Senate will not go into formal legislative process. If the vote is successful, it would not mean that the bill would pass. Before a final vote, senators may debate, amend and negotiate further changes to the bill.
The legislation would create federal rules for digital asset markets, with the CFTC and Securities and Exchange Commission having a split of responsibilities. The way it treats DeFi might also decide which projects will be subject to direct federal oversight.
In some aspects, the new language is more precise for the crypto industry. The bipartisan team for passage, however, is still in jeopardy due to the unresolved ethics fight and the stablecoin rewards dispute.
The September vote will then ensure that the most recent compromises can pass. For now, Republicans have tackled some of the technical disagreements, but not the political disagreements regarding ethics.