Key Insights:
- The facility offers significant extra borrowing power, but no assurances of financing.
- New share sales can lead to dilution, especially when it comes at a lower price.
- Access to the full facility may depend on higher share prices or shareholder approval.
Hyperliquid Strategies increased its Chardan Capital Markets equity facility to $2.5 billion on Sept. 1. The move expands its potential funding pool for HYPE purchases while raising dilution concerns for existing shareholders.
The Nasdaq-listed company disclosed the amendment in a Form 8-K filed with the U.S. Securities and Exchange Commission. The agreement raises the original $1 billion facility by another $1.5 billion.
However, the expanded figure does not represent cash already raised. Instead, it marks the maximum amount available under the revised equity purchase agreement.
Today we filed an 8K explaining the details of our updated equity facility.
When we originally put this facility in place it had a headline of $1bn (which at the time seemed like an awful lot). We are now close to hitting the $1bn limit, so we have increased the agreement to… pic.twitter.com/OsbcpogT67
— David Schamis (@dschamis) September 1, 2026
A larger funding pipeline emerges
Hyperliquid Strategies can direct Chardan to purchase newly issued common shares under specified conditions. Chardan can then resell those shares in the public market.
The company controls the timing and size of individual transactions. Market conditions, trading prices and other contractual requirements can influence each sale. The arrangement gives Hyperliquid Strategies another route to finance its HYPE-focused treasury strategy. However, every new share issuance can reduce existing investors’ ownership percentage.
The company had already raised $646.6 million through the facility by August. It used financing alongside other resources to expand its HYPE holdings substantially.
Hyperliquid Strategies reported about 29.3 million HYPE tokens in its treasury. It had spent approximately $773.4 million acquiring 16.5 million tokens at an average $46.77. The company also reported about $149.9 million in cash at the end of June. It carried no debt at that point.
The $12.02 threshold changes the equation
The amended agreement includes a specific limitation for lower-priced share sales. After cumulative facility purchases reach $1 billion, sales below $12.02 face a 42,641,847-share cap.
That figure represents 19.99% of the company’s pre-amendment outstanding shares. Nasdaq rules generally require shareholder approval for certain discounted issuances above that threshold. As a result, the company cannot automatically access the entire $2.5 billion facility at any stock price.
PURR closed at $11.36 on Sept. 1, according to the supplied market data. The shares fell about 7.3% during regular trading. The stock opened at $11.76 and reached an intraday high of $12.31. Trading volume reached roughly 24.3 million shares.
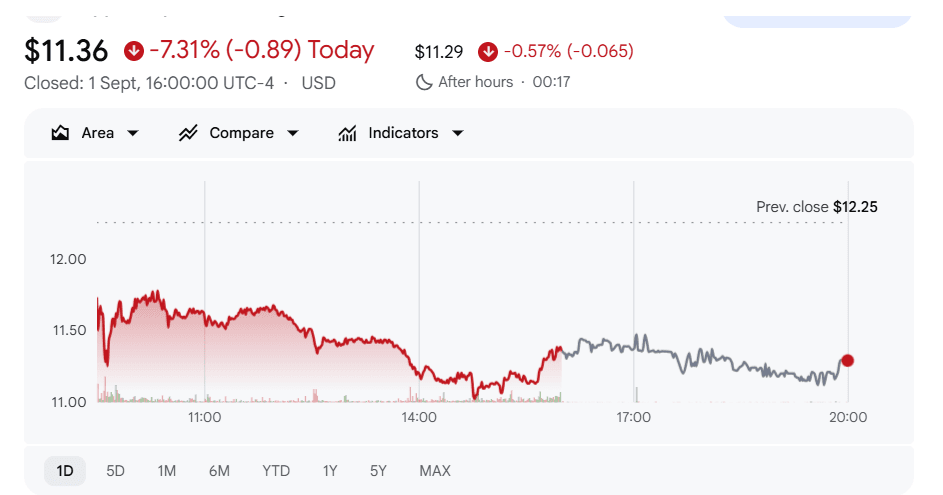
Importantly, a price below $12.02 does not automatically trigger the restriction. The limit applies to qualifying sales after cumulative purchases reach $1 billion.
HYPE growth adds another layer
The expanded facility comes after a sharp rise in market interest surrounding Hyperliquid. HYPE gained more than 20% in August after U.S. President Donald Trump discussed potential U.S. regulatory treatment for the trading platform.
Trump said Commodity Futures Trading Commission Chair Michael Selig was working toward bringing Hyperliquid into the United States legally and compliantly.
Hyperliquid Strategies shares gained 30.4% after those remarks. The subsequent pullback now places the stock below the amended facility’s $12.02 reference price. Meanwhile, HYPE remains central to the company’s balance sheet. The treasury strategy effectively links the company’s equity valuation with the performance of Hyperliquid’s native token.
There is opportunity and risk within the relationship. HYPE prices can go up if the treasury value can go up. When token prices are low , they can pressure the company’s assets .
The government’s strategy is put to the test
Hyperliquid Strategies is a result of a reverse merger with Sonnet BioTherapeutics in December 2025. Since then, its corporate strategy has centered heavily on accumulating HYPE.
The company also bought back 5.8 million shares at an average price of $4.80 when its stock traded below its perceived asset value.
That approach differs from the current financing environment. With PURR near its estimated net asset value, new equity sales offer less obvious value to existing holders. The structure also faces another supply challenge. About 14.18 million HYPE tokens became unlocked on Aug. 29, adding significant potential supply to the market.
At the same time, Hyperliquid’s Assistance Fund continues buying HYPE with trading fees. The fund has accumulated roughly 44.4 million tokens through automated purchases and burns.
Therefore, Hyperliquid Strategies now operates alongside a protocol-level buyer. Its expanded equity facility could provide another source of demand, but only when financing conditions support further purchases.
Conclusion
Hyperliquid Strategies has increased its potential funding capacity without raising the full $2.5 billion. The revised Chardan facility provides much more flexibility for management, but it is very much reliant on the price of PURR’s trading.
When shares drop below $12.02, the limits of the issuance of the agreement get more important. This has put the company’s HYPE accumulation plan in a new position of funding, dilution and market valuation.